The PayPal Cashback Mastercard pays a flat 2% cashback on eligible purchases. The same card also charges a 3% foreign transaction fee, so a purchase from an overseas seller can leave you 1% behind.
That math gets buried under the friendly parts: no annual fee, unlimited rewards, and cashback that lands in your PayPal balance right away. All true. But where you spend decides whether the card pays you or charges you.
This review is for US-based PayPal regulars who shop online a lot, including people who buy from international stores and want to know if one simple card can handle everything.
Is the PayPal Cashback Mastercard Worth It in 2026?
For domestic spending, yes, it can be a strong everyday card. The PayPal Cashback Mastercard is a no-annual-fee credit card issued by Synchrony Bank that pays unlimited 2% cashback on eligible purchases.
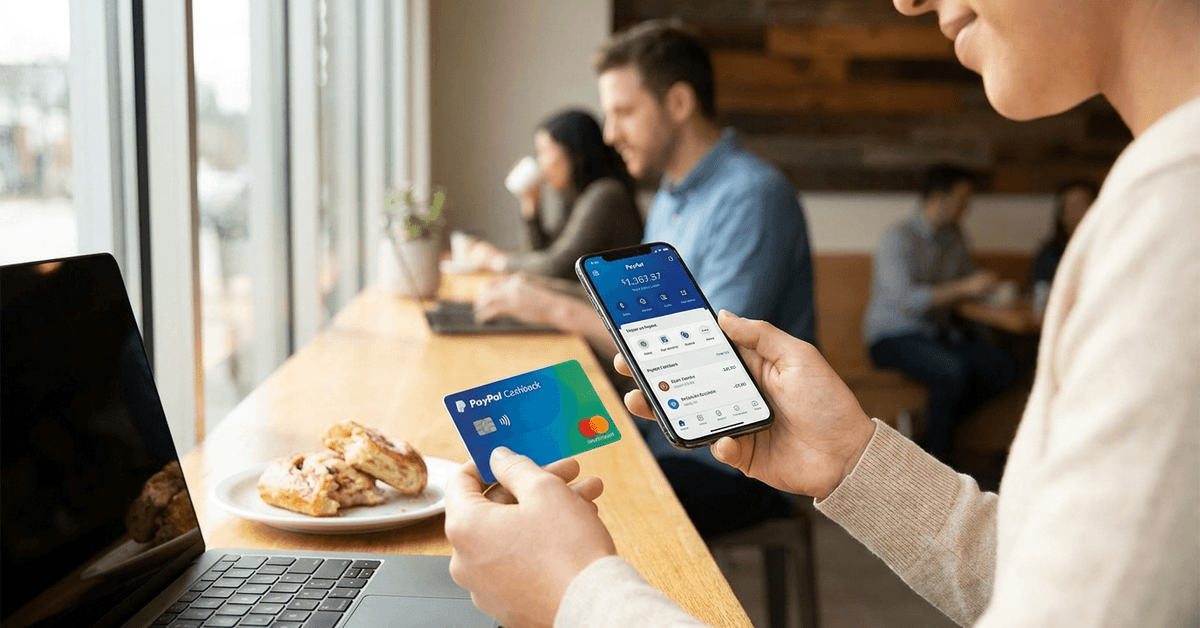
There are no bonus categories, no rotating calendars, and no spending caps. You swipe, you earn 2%, and the reward shows up in your PayPal account without waiting for a statement cycle or a minimum balance.
What 2% looks like on a normal month
Spend $1,000 on groceries, gas, and online orders, and you earn $20 back. Spend $1,500, and it's $30. No category matching required, which is great news if tracking reward calendars sounds like homework.
The trade-off is plain. Cards with bonus categories can pay more on specific spending like dining or travel, so a flat 2% card will lose to them in those niches.
Where the card starts working against you
The 3% foreign transaction fee hits purchases made abroad or on non-US sites. A $200 order from an overseas shop earns $4 in cashback and costs $6 in fees. You end up $2 down.
So the honest verdict depends on one question: how much of your shopping happens outside the US? If it's close to zero, this card gets interesting.
What Fees Does the PayPal Cashback Mastercard Charge?
The fee sheet is short, which helps. The PayPal Cashback Mastercard has no annual fee, no monthly service fee, a 3% foreign transaction fee, and a balance transfer fee that typically sits at 3% of the transferred amount.
Some cardholders report balance transfer rates that shift depending on promotions or creditworthiness. Treat 3% as the baseline and confirm the current number on your offer before moving any debt.
Late and returned payment penalties
Late payments trigger a fee, and returned payments carry a penalty too. Either one can wipe out months of 2% rewards on a modest spending budget, so autopay for at least the minimum is worth setting up on day one.
The APR on purchases
The variable purchase APR sits within the typical national range for rewards cards, based on your credit profile. It won't shock you, and it won't impress you either.
Carry a balance and the interest eats your cashback fast. Pay the full statement balance each month, and the APR stops mattering at all.
How Does the 2% Cashback Hold Up by Transaction Type?
Your net return changes depending on what you're buying and where. On domestic purchases, the PayPal Cashback Mastercard returns a net 2% when the balance is paid in full each month.
The table below compares the most common ways people use the card.
| Transaction type | Cashback earned | Fee charged | Net result |
|---|---|---|---|
| US store or US website | 2% | None | +2% |
| Overseas website or travel abroad | 2% | 3% foreign fee | -1% |
| Balance transfer | None | Typically 3% | -3% upfront |
| Purchase carried past due date | 2% | Variable APR interest | Usually negative |
Keep this card inside US borders and pay it off monthly, and the math stays in your favor.
The PayPal balance angle
Your cashback goes straight into your PayPal account, ready to use immediately. For heavy PayPal users, that means rewards can pay for the next online order without touching your bank.
There's a quiet risk there. Rewards that sit in a spending wallet tend to get spent. If you want the 2% to build up, move it to savings now and then.
Why I'd Skip the Signup Bonus Chase Here
The usual advice says to choose your next credit card based on the welcome bonus. I think that logic falls apart for a card you plan to keep for years, and the PayPal Cashback Mastercard proves it: zero signup bonus, but 2% with no earning cap.
A one-time bonus pays once. A flat 2% keeps paying on every eligible purchase, month after month, with no annual fee eating into it. Over a long stretch, steady rewards on everyday spending can outweigh a single upfront perk.
You can push back on this, and fair enough. If you'll hit a big bonus requirement easily and then switch cards, the bonus route may come out ahead. Card churners play a different game than people who want one card and done.
Who flat-rate cashback fits best
This card may suit you if your spending looks like this:
- You already use PayPal for shopping, transfers, or invoicing
- Most of your purchases happen at US stores and US websites
- You pay the full statement balance every month
- You'd rather earn 2% everywhere than juggle bonus categories
Who should look elsewhere
Frequent travelers and anyone buying often from overseas sellers will feel that 3% foreign fee. Rewards optimizers who want travel points or premium insurance perks won't find them here either.
How to Apply for the PayPal Cashback Mastercard Safely
The only official way to apply is by logging into your PayPal account and opening the PayPal Mastercard page under the Credit section. You can also start from the official PayPal Cashback Mastercard page.
Ignore emails, texts, or ads with "pre-approved" links. If it doesn't route through your logged-in PayPal account, don't type your details into it.
Credit score and documents you'll need
Approval usually goes to applicants with good to excellent credit, generally above 670. Some people with thinner credit files get approved, especially with an active PayPal history, but nothing is guaranteed.
The application asks for:
- Your legal name and home address
- Your Social Security number
- Employment and income details, mainly when your credit file shows gaps
What happens after you hit submit
The application gets verified almost instantly, starting with a soft credit check. If approved, your card details are ready for online use right away, and the physical card ships to your registered address.
Mistakes to avoid when applying
A few small slips can cost you:
- Applying through a third-party link instead of your PayPal account
- Entering income that doesn't match what your credit file suggests
- Assuming approval is automatic because you've used PayPal for years
- Forgetting to set up autopay before the first statement arrives
Is the PayPal Cashback Mastercard Secure?
Yes, the security setup is solid for everyday use. The card is issued by Synchrony Bank, which runs fraud monitoring on card activity.
Purchases made through PayPal can also fall under PayPal's buyer protection policies, which help with disputes and unauthorized charges. Most credit cards offer similar coverage, but managing claims inside an app you already know is handy.
What the card doesn't include
There's no travel insurance package, no premium perks, and no introductory bonus. Expect a clean cashback tool and nothing fancier. Honestly, for some people, fewer features means fewer things to forget about.
Questions People Ask About the PayPal Cashback Mastercard
A few questions come up again and again, so these answers fill in the gaps.
- Q: Can I use the PayPal Cashback Mastercard outside PayPal?
Yes, it works anywhere Mastercard is accepted, online or in physical stores. The 2% applies to eligible purchases whether or not PayPal is involved at checkout. - Q: Does applying for the PayPal Cashback Mastercard hurt my credit score?
The initial check is a soft credit check, which doesn't hurt your score. If you're approved and open the account, expect normal account reporting from Synchrony afterward. - Q: Is there a limit on how much cashback I can earn?
No cap at all. Spend more on eligible purchases and the 2% keeps adding up, which is a big reason simplicity fans like this card. - Q: Should I use this card for a balance transfer?
Probably only after checking your specific offer. With a balance transfer fee typically around 3%, the upfront cost needs to beat the interest you'd save elsewhere. - Q: Can I get the card if I don't have a PayPal account?
No, you apply through a PayPal account, so you'll need to create one first. An active account history may also help your chances during review.
Conclusion
The PayPal Cashback Mastercard pays a flat 2% with no annual fee, which suits steady domestic everyday spenders. Its 3% foreign transaction fee turns overseas purchases into a net loss of around 1% each time.
Regular PayPal users who pay in full monthly will likely get the most real value from it. So check where your money goes each month, then decide if this card earns a permanent wallet spot.